

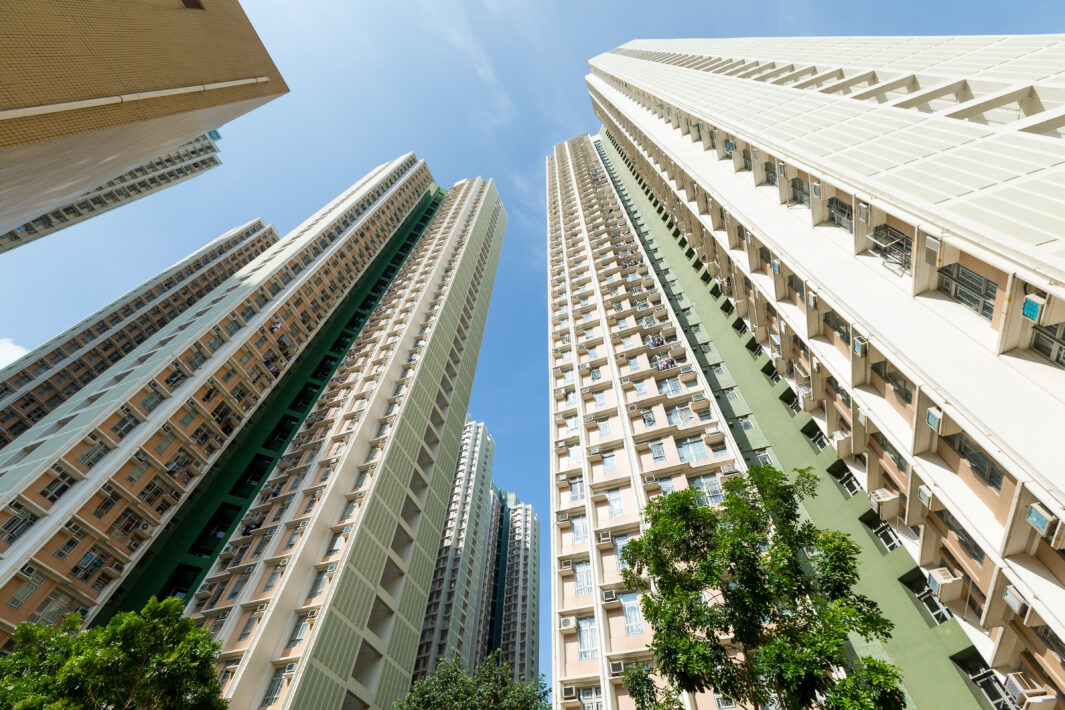

The recent divergence between resale HDB and private housing price indexes has fuelled speculation that Singapore’s residential property market is splitting into two separate worlds and created fear that some Singaporeans might miss out forever if they do not upgrade to a private home now.
To understand why, look at the latest HDB resale price index, which fell by 0.3 per cent, marking a third consecutive quarterly decline. Over the same period, the Urban Redevelopment Authority’s private residential property price index rose by 0.5 per cent, extending a seven-quarter run of price growth, albeit at a slower pace.
Indeed, nearly a third of property sector veterans surveyed by the Institute of Real Estate and Urban Studies at the National University of Singapore believe that both markets are structurally decoupling.
But the evidence suggests short-term price movements should not be mistaken for structural separation. Markets are truly decoupled only when prices in one no longer influence the other because buyers no longer substitute between them.
The three quarters of divergence in price growth between the public resale market and the private markets do not prove this, and less so when you consider that both indexes over the last two decades show remarkable synchronicity.
Economists describe this as cointegration: Prices may drift apart temporarily, but remain anchored by common fundamentals and shared buyer behaviour over time.
Interconnected segments
If anything, the resale HDB and private residential markets remain closely linked through overlapping buyer pools, household upgrading and downgrading, and the expectation that homes preserve wealth over time.
Singapore’s housing market is better characterised as a hierarchy of interconnected segments, rather than two mutually exclusive markets.
The hierarchy exists both in terms of housing type and price. At one end are Build-To-Order (BTO) or resale HDB flats, while at the other are landed homes and good class bungalows. It would be unrealistic to expect an overlap between buyers in these two segments because affordability constraints naturally separate them.
The overlap lies in the middle of the housing ladder. A household earning around $10,000 a month, for example, may be able to choose between a BTO flat, a resale HDB flat, an executive condominium and an entry-level mass-market private condominium, depending on its financial circumstances and housing preferences.
It is precisely these overlapping buyer pools that transmit price movements between adjacent housing segments.
Residential mobility further reinforces these linkages. Many young households begin with subsidised BTO flats. After fulfilling the minimum occupation period, they may sell their first home and use the accumulated housing equity to finance the purchase of a larger resale flat or a private condominium.
The capital appreciation realised from the resale of the starter home partially finances this transition up the housing ladder, creating a “ripple” effect between the two markets.
Conversely, some older households move in the opposite direction, selling private homes and downsizing to resale flats to unlock housing wealth for retirement.
As households upgrade and downgrade over their life cycle, price appreciation in one segment affects purchasing power in the next. This organic mobility helps explain why resale HDB and private residential markets continue to move together over the longer term, even when their short-term price trajectories differ.
Also notable is that neither market is homogeneous and an uptick in the private home price index does not imply a uniform rise in prices of all private homes. This recent second-quarter growth for 2026 has been driven largely by landed housing and non-landed private housing in the Core Central Region, while other private housing segments have recorded much weaker performance.
Likewise, the resale HDB market consists of flats with very different lease balances, locations, accessibility and neighbourhood amenities. Individual housing prices reflect these heterogeneous property attributes, which remain important determinants of value alongside broader market conditions.
Changes in the overall resale price index may therefore reflect shifts in the mix of transactions or the characteristics of homes sold, rather than a broad-based decline in the value of all resale flats.
Buyer behaviour
The greater risk is that misplaced fears of decoupling encourage fear-driven buying. Recent private residential launches with exceptionally strong take-up rates have reinforced concerns that buyers may be priced out if they do not act quickly.
Such behaviour differs from the gradual upgrading process that has traditionally characterised Singapore’s housing market. Fear-based buying often reflects expectations that prices will continue rising indefinitely, inducing households to purchase properties beyond their financial means or to advance their upgrading plans prematurely.
Our analysis of transactions involving private non-landed homes sold twice over a specific period suggests buyers have been holding properties for progressively shorter periods. The average holding period of this group fell from around 120 months for homes bought in the early 2000s to less than 10 months for homes purchased between 2020 and 2025.
Yet shorter holding periods did not translate into higher returns. Buyers who entered the market during the post-pandemic boom earned average holding-period gains of just 0.95 per cent, compared with 47.2 per cent for those who bought during the weaker market conditions of the early 2000s.
The lesson is that rising markets do not guarantee superior investment outcomes.
Buyers should also be mindful of the cyclical nature of the housing markets.
China’s prolonged property correction serves as a useful reminder that housing cycles do not move in only one direction. When expectations of perpetual price appreciation become detached from underlying fundamentals, market corrections can be deep and persistent.
The recent divergence between resale HDB and private residential prices should therefore be interpreted with appropriate caution.
The article was first published on The Straits Times.